Insights

Momentum Newsletter | October 2026

October 22, 2026
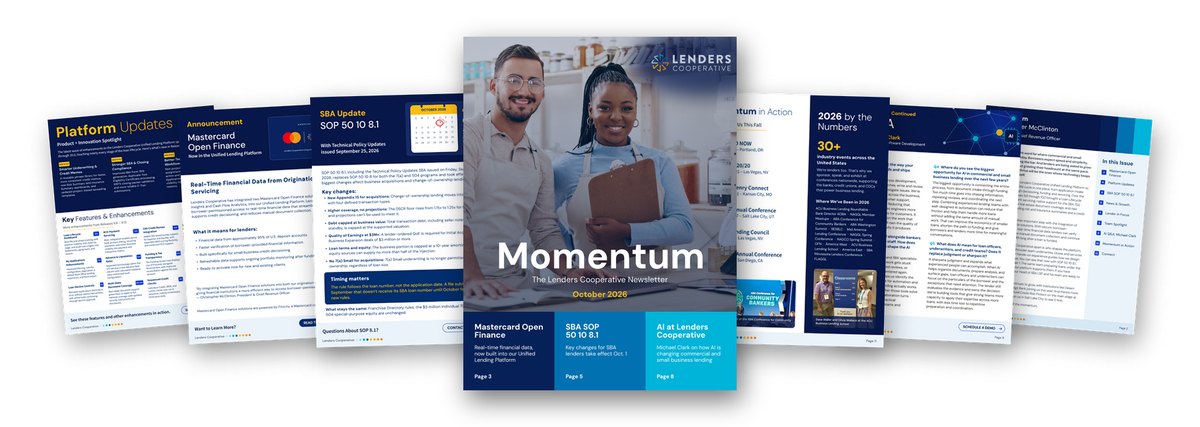
October 2026

Momentum

The Lenders Cooperative Newsletter

Letter from the President

These are heady days at Lenders Cooperative

These are heady days at Lenders Cooperative. The team members here know that something special is taking shape. The platform that we have engineered is becoming increasingly durable, adaptive, and adopted by the largest commercial lenders in the U.S. banking industry. Not everyone gets an opportunity to be a part of something like that in their careers, so I’m taking a moment for gratitude and recognition of this team.

I haven’t been more energized and inspired by a team of builders in quite some time, and I’ve had the privilege of working with some of the legends of fintech. Whether we are showing up every day at Mechanicsburg, Arlington, our Birmingham HQ, or remote offices, everyone on this team is digging deep right now, because we must. We are getting tested and we are accepting the challenges, and we’re passing the tests.

Over the course of this year, LC has entered another level of technology provision and service. We’ve crossed the threshold of software provider to system of record partner, supporting core lending operations at Tier 1 financial institutions. Taking a $200 billion FI through vendor due diligence, exhaustive UAT, and into production with closed and funded loans is an exercise that will test the mettle of a company and change it irrevocably. And for the better. We’re moving forward with higher expectations for our platform, our people, and our customers’ outcomes. That bar will only move higher now. And that creates an unmistakable momentum within a company, and we hope you feel it when you engage with us.

Keep an eye on LC, because this is getting super interesting. In the last few days we signed a $25 billion bank and one of the largest non-bank commercial lenders in the world, introduced a next-generation servicing platform to complement our origination workflow, and at the upcoming ABA Annual Conference, we’ll announce an innovative new credit risk transfer product that’s going to knock your socks off. Much more to come.

Chris McClintonPresident & Chief Revenue Officer

Announcement

Mastercard Open Finance, now in the unified lending platform

Lenders Cooperative has integrated two Mastercard Open Finance solutions, Payment Risk Insights and Cash Flow Analytics, into our unified lending platform. Lenders get secure, borrower-permissioned access to real-time financial data that streamlines underwriting, supports credit decisioning, and reduces manual document collection.

What it means for lenders

  • Financial data from approximately 95% of U.S. deposit accounts
  • Faster verification of borrower-provided financial information
  • Built specifically for small business credit decisioning
  • Refreshable data supports ongoing portfolio monitoring after funding
  • Ready to activate now for new and existing clients
Lenders Cooperative integrates Mastercard Open Finance

“By integrating Mastercard Open Finance solutions into both our origination and servicing workflows, we’re giving financial institutions a more efficient way to access borrower-permissioned financial information.”

Christopher McClinton, President & Chief Revenue Officer

Mastercard Open Finance solutions are powered by Finicity, a Mastercard company.

Product + Innovation Spotlight

Platform Updates

The latest wave of enhancements to the Lenders Cooperative unified lending platform spans Releases 9.8 through 10.0, touching nearly every stage of the loan lifecycle. Here’s what’s new in Release 10.0:

New in 10.0

Smarter Underwriting & Credit Memos

A reusable phrase library for faster, more consistent credit memos, new Risk Summary and Insurance Summary dashboards, and updated project-based spreading templates.

New in 10.0

Stronger SBA & Closing Compliance

Improved SBA Form 1919 generation, duplicate-free Eligibility Certificate processing, WKFS closing packet validation, and more reliable E-Tran submissions.

New in 10.0

Better Team & Borrower Workflows

New project and loan team assignments, configurable adverse action and Notice of Incomplete Application letters, and earlier visibility into document rejection reasons.

More from Releases 9.8 – 9.12

Key features & enhancements

Loan Lifecycle Dashboard 9.12

New lifecycle phase tracking with pipeline visibility, drill-down by stage, and audit-trail insights into bottlenecks, aging loans, and rework.

ACH Payment Servicing 9.12

Moov integration enables secure bank account linking, recurring payments, and richer borrower visibility into payment and transaction history.

CRS Credit Bureau Integration 9.12

Added CRS-based bureau support for Experian and Equifax, with expanded SBSS scoring flexibility and continued FICO support.

Guaranty & SBA Workflows 9.11

Limited and Full Guaranty selection in Borrowing Structure, auto-populated into Underwriting, with an enhanced non-blocking Form 1919 flow.

My Applications Enhancements 9.11

Improved filtering, column configuration, pagination, a default Back Office landing experience, and Excel export.

Advance & Liquidation Rates 9.10

Separated terminology within the LTV table plus a new Advance Rate column with calculated collateral value and tenant-level configuration.

Funding & Fee Transparency 9.10

The Funding Screen now displays Use of Proceeds alongside financed fees, with improved reconciliation against the loan amount.

SBA 7(a) MARC Program 9.9

Native support for MARC Lines of Credit and Term Loans, with automated eligibility validation and enforced loan-size and guaranty limits.

Loan Decline Controls 9.9

Reinstate applications declined in error without admin intervention, with active tasks continuing through decline approval.

Multi-State Document Coverage 9.9–9.12

Real estate document support grows from 15 states to full national coverage, with updated security instruments and disclosures.

Sequenced Credit Checks 9.8

Individual Credit, SBSS, and Lumos checks now run in sequence, cutting unnecessary third-party pulls.

Work Management Redesign 9.8

A uniform, table-driven task workflow across Underwriting, Doc Prep, Pricing, and more, with fewer pop-ups.

SBA Update

SOP 50 10 8.1 is now in effect

SOP 50 10 8.1, including the Technical Policy Updates SBA issued on Friday, September 25, 2026, replaces SOP 50 10 8 for both the 7(a) and 504 programs and took effect October 1. The biggest changes affect business acquisitions and change-of-ownership lending.

EffectiveOct. 12026 · Loans receiving an SBA loan number on or after this date
  • New Appendix 15 for acquisitionsChange-of-ownership lending moves into its own appendix with four defined transaction types.
  • Higher coverage, no projectionsThe DSCR floor rises from 1.15x to 1.25x for first-time buyers, and projections can’t be used to meet it.
  • Debt capped at business valueTotal transaction debt, including seller notes not on full standby, is capped at the supported valuation.
  • Quality of Earnings at $3M+A lender-ordered QoE is required for Initial Acquisition and Business Expansion deals of $3 million or more.
  • Loan terms and equityThe business portion is capped at a 10-year amortization, and limited equity sources can supply no more than half of the injection.
  • No 7(a) Small for acquisitions7(a) Small underwriting is no longer permitted for any change of ownership, regardless of loan size.

Timing matters

The rule follows the loan number, not the application date. A file submitted in late September that doesn’t receive its SBA loan number until October falls under the new rules.

What stays the same: Franchise Directory rules, the $5 million individual 7(a) maximum, and 504 special-purpose equity are unchanged.

News & Growth

New partners on the platform

Desert Financial Selects Lenders Cooperative to Power Commercial and SBA Lending

Arizona-based Desert Financial, a $9 billion credit union serving more than 500,000 members, is now live on our end-to-end business lending platform and uses our outsourced operational support across underwriting, processing and servicing.

Liberty Savings Bank Selects Lenders Cooperative to Advance Commercial and SBA Lending Strategy

Liberty Savings Bank, a community-focused institution serving Sarasota and Manatee counties in Florida, is bringing its commercial and SBA lending, from origination through servicing, into one streamlined platform to reduce friction and speed up funding.

“We were looking for a solution that could adapt to our processes—not force us into a rigid model—and Lenders Cooperative gives us that balance of control and efficiency.”

Scott Holmer, SVP – Commercial Lending
Lender in Focus

Desert Financial

Based in Arizona, Desert Financial is a $9 billion credit union serving more than 500,000 members nationwide. It is now in production on the Lenders Cooperative end-to-end business lending platform to support the growth of its commercial and SBA lending programs.

Desert Financial uses the platform to automate origination workflows, speed up time to close, and give business members a modern digital borrowing experience. It also relies on Lenders Cooperative’s outsourced operational support to add capacity across underwriting, processing, and servicing, scaling efficiently while maintaining compliance and credit quality.

“Our focus is on delivering fast, reliable access to capital for our business members.”

Andrea Mosher, Chief Lending Officer

“With Lenders Cooperative, we’ve implemented a modern lending infrastructure that combines powerful technology with the operational support needed to grow our commercial and SBA lending programs with confidence.”

Team Spotlight
Michael Clark

Michael Clark

Director of Software Development

Michael leads the engineering team behind the Lenders Cooperative unified lending platform. He brings more than 20 years of experience across security, hardware, networking, software design, and product lifecycle management.

A Triplebyte Certified Engineer, Michael focuses on building secure, user-friendly products and is always learning and exploring new ways to apply technology.

“What excites me most is combining our people’s expertise with AI tools designed for the work they do. That gives every team more capacity and helps move loans from document intake through funding with less friction.”

AI Q&A with Michael Clark

We sat down with Michael to talk about how Lenders Cooperative is putting AI to work, the opportunity it creates for lenders, and what it means for the industry.

Q1How is Lenders Cooperative using AI in the unified lending platform today, and where are lenders seeing it first?

Credit memos are one visible example: AI helps teams draft, summarize, and refine the narrative. We’re also building custom products that use large language models to streamline the broader lending process, from document intake through funding. That means connecting information, reducing repetitive work, and helping teams move a loan forward with fewer manual handoffs. The goal is to put AI to work throughout the process so lenders can spend more time on borrowers and credit decisions.

Momentum in Action

Where to find us this fall

  • NADCO NOWOct. 6–9 · Portland, OR
  • Money20/20Oct. 18–21 · Las Vegas, NV
  • Jack Henry ConnectOct. 19–21 · Kansas City, MO
  • ABA Annual ConferenceOct. 25–27 · Salt Lake City, UT
  • ACU Lending CouncilNov. 3–6 · Las Vegas, NV
  • NAGGL Annual ConferenceNov. 3–5 · San Diego, CA
30+

industry events across the United States in 2026

We’re lenders too. That’s why we sponsor, speak, and exhibit at conferences nationwide, supporting the banks, credit unions, and CDCs that power business lending.

Where we’ve been in 2026: ACU Business Lending Roundtable · Bank Director AOBA · NAGGL Member Meetups · ABA Conference for Community Bankers · ABA Washington Summit · SESBLC · Mid America Lending Conference · NAGGL Spring Conference · NADCO Spring Summit · OFN · America West · ACU Business Lending School · America East · SBA Minnesota Lenders Conference · FLAGGL

Connect

Get in touch with Lenders Cooperative

Interested in learning more? We’d love to hear from you. Let us know how we can help.